






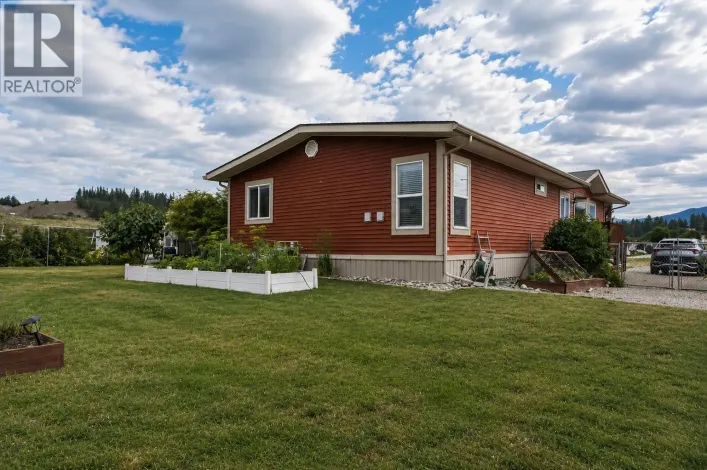


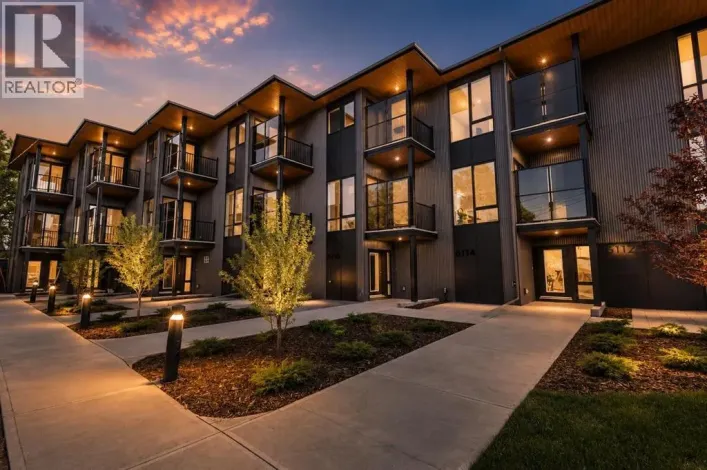




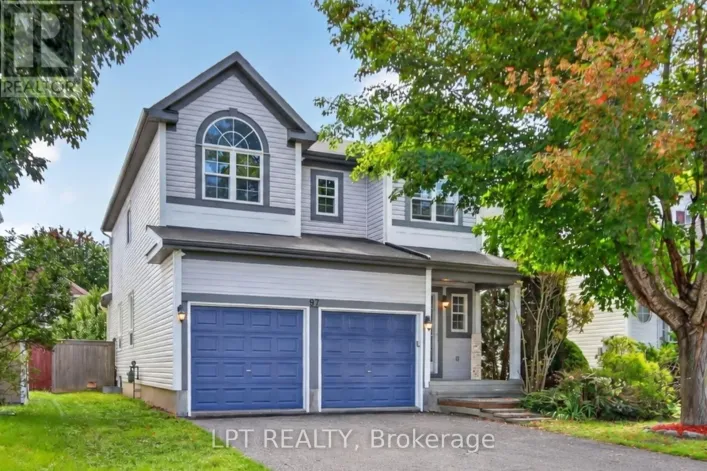


Properties advertising assumable mortgages
Compare properties whose original listings advertise an existing mortgage or property financing that a purchaser may be able to assume. Offers can include individual homes, apartment buildings, mixed-use assets and other investment properties. Some listings describe a possibility or require the buyer to assume existing financing; neither wording establishes that a particular buyer is approved.
Confirm the financing with the lender
The Financial Consumer Agency of Canada explains that the lender must approve a buyer who wants to assume a mortgage. Ask for the current balance, interest rate, remaining term, payment schedule, fees and written assumption requirements. Published figures can change or become outdated. Listing claims are not independent confirmation of approval, availability or savings.
A lease is not a mortgage
An assumable land lease, business lease, solar agreement, furnace contract or warranty is different from taking over property financing. A tenant remaining in place, rental income described as a mortgage helper, or an illustrative cash-flow calculation also does not establish that the mortgage is assumable. Seller financing and a portable mortgage are separate arrangements and should not be treated as equivalent without property-specific confirmation.
Compare the actual purchase
Review the offered property, purchase price, financing balance and any additional funds needed to complete the purchase. For investment properties, check the exact buildings and units included, leases, expenses and condition. Confirm the current offer and financing documents with the listing contact, lender and your independent advisers before relying on advertised terms.